Leveraged ETFs: Daily Targets and Multi-Day Compounding
Calculate how a daily leveraged target compounds across different paths, why exposure resets, and where a simple model stops describing a real fund.
Written by James Lipyeat · Founder, Ironclad Research
Reviewed 13 October 2026 · Editorial policy
Before this, read
The horizon is part of the objective
A leveraged ETF combines a fund structure with an exposure objective. A label such as “2x” is incomplete without the benchmark, direction, measurement interval and treatment of fees. A daily target is a statement about a particular daily return calculation. It is not a promise that multiplying an index's annual return by two will reproduce a shareholder's annual result.
This lesson models positive daily leveraged exposure for education. It applies across regions, uses dollars and does not teach country-specific account or tax rules. Every path and balance is fictional. Read What Is An ETF?, Compound Growth and Expense Ratios & Fund Costs first.
As a labelled US-listed example, ProShares SSO states an objective of twice the S&P 500's daily performance before fees and expenses, verified 13 October 2026. The issuer distinguishes that objective from results over other holding periods. This identifies a target, not a guaranteed achieved return or a recommendation. Source: ProShares SSO product information.
The SEC staff's investor bulletin explains daily resets, longer-horizon divergence and the use of derivatives in these products. This is educational guidance, not a claim that every leveraged product has identical terms. Source: Updated Investor Bulletin: Leveraged and Inverse ETFs, 29 August 2023; verified 13 October 2026.
Write the ideal model before using it
Let the benchmark's return over day t be r(t), expressed as a decimal. Let the target multiplier be L. In an idealised exact-tracking model with no expenses, financing drag, transaction costs, distributions or cash flows, the fund's daily wealth factor is 1 + L × r(t). Multiply the previous day's wealth by that factor to obtain the new value.
The benchmark's multi-day factor is the product of its daily factors, 1 + r(t). The fund's multi-day factor is the product of 1 + L × r(t). Those are different products. Multiplying the benchmark's final cumulative return by L is a third calculation and generally does not equal the fund result.
For example, a 3% benchmark day gives a +6% daily return in an ideal +2x model. A $100 starting balance becomes $106. A -3% benchmark day gives -6%, taking the same starting balance to $94. These isolated calculations establish the target arithmetic, not the outcome of a sequence of days.
The model assumes each wealth factor remains meaningful and non-negative. It also assumes the reference return and the fund measurement interval match. A price-only benchmark, total-return benchmark, intraday purchase and close-to-close target must not be mixed without explaining the differences. These assumptions are part of the calculation, not optional footnotes.
Equal endpoints can hide different paths
Compare two original two-day scenarios, both beginning with a benchmark value of 100. In the first, the benchmark is unchanged each day. In the second, it rises 25% to 125, then falls 20% back to 100. Both scenarios have a zero cumulative benchmark return.
An ideal +2x daily model starting at $100 stays at $100 on the flat path. On the round-trip path it rises 50% to $150, then falls 40% to $90. It loses 10% even though the benchmark finishes unchanged. No fee, tracking failure or forecast is needed to produce that result; it follows from the specified sequence of returns.
The second day's 40% fund loss is measured against $150, so it removes $60. It does not remove 40% of the original $100. Adding +50% and -40% would incorrectly suggest a +10% result. Returns compound on the value that actually exists at the start of each interval.
Notice also that +25% and -20% are the benchmark moves needed for this particular round trip. Equal positive and negative percentages do not generally cancel. The percentage required to return to a starting value depends on the level from which that second move begins.
Compounding is not an always-loss rule
Now assume the benchmark gains 5% on each of two days. It grows from 100 to 105 to 110.25, a 10.25% cumulative gain. The ideal +2x model gains 10% each day and grows from $100 to $110 to $121, a 21% cumulative gain.
Twice the benchmark's cumulative return is 20.5%, which is lower than 21%. The difference does not prove a fund has exceeded its daily mandate; the model hit that mandate exactly on both days. The comparison simply uses two different compounding calculations.
This is why “leveraged ETFs always decay” is too broad as a mathematical statement. The round trip and the steadily rising path give different relationships to the simple multiple. Neither scenario establishes which path will occur next. A useful explanation describes the mechanism and its conditions rather than substituting a slogan for the calculation.
Two falling days also deserve their own calculation. With benchmark returns of -5% and -5%, the benchmark loses 9.75%; an ideal +2x model loses 19%, ending at $81. That is different from twice -9.75%, or -19.5%. Being less negative than that particular comparison does not make a 19% loss small or desirable.
Calculate a longer path without shortcuts
Take three fictional benchmark returns: +2%, -1% and +3%. The cumulative benchmark factor is 1.02 × 0.99 × 1.03 = 1.040094, a 4.0094% gain. Summing the daily percentages gives 4%, close but not exact.
For an ideal +2x model, use daily returns of +4%, -2% and +6%. Starting with $100 gives $104 after the first day, $101.92 after the second and $108.0352 after the third. The cumulative return is 8.0352%. Twice the benchmark's cumulative result is 8.0188%, so even this modest path produces a difference.
A spreadsheet exercise should carry full precision between rows and round only displayed results. Premature rounding can obscure small differences or create apparent tracking errors. Each row should show the benchmark return, multiplier, fund factor, starting wealth and ending wealth so another reader can identify the first inconsistent step.
The ideal final product is unchanged if the identical set of daily returns is merely rearranged. Multiplication is commutative. “Path dependence” here means that a benchmark endpoint alone is insufficient: different sets of daily moves leading to that endpoint can produce different leveraged results. It does not mean that reordering the same frictionless factors must change their final product.
Order can still affect interim drawdowns, the timing of external cash flows and real-world operations. Those are additional features of a more detailed model. Separating them avoids using a true statement about some real-world paths to justify an incorrect claim about the simplified arithmetic.
Why exposure resets
Use a simplified linear-exposure portfolio with $100 of net assets and $200 of benchmark exposure. Ignore financing and all other costs. A 10% benchmark rise creates a $20 gain, taking net assets to $120. If the original exposure has grown with the benchmark to $220, it is now about 1.83 times net assets, not two times.
Restoring the +2x target requires $240 of exposure, twice $120. The model therefore adds $20 of exposure. Exposure is an economic notional here, not a statement that the fund spends $20 cash on ordinary shares. A real implementation can use instruments whose cash and collateral arrangements differ.
After a 10% benchmark decline instead, net assets fall to $80 and the original exposure becomes $180. That is 2.25 times net assets. Restoring +2x requires reducing exposure to $160. The model removes $20 of exposure after the loss. The reset responds to a changed wealth base; it is not a discretionary forecast about the next day's direction.
A fund target is not an account loan
The examples assume shares bought fully with cash. Fund-level leverage affects the value of those shares. A margin loan in the investor's account would add separate interest, collateral and account obligations. Combining the two without modelling both layers would understate the complexity of the exposure.
Compare a fictional daily-reset fund with a static borrowed portfolio. Both can begin with $100 equity and $200 exposure. After a market move, a static arrangement retains its borrowing unless changed, while the reset model adjusts exposure relative to new net assets. Equal initial leverage therefore does not imply equal future leverage or identical multi-day returns.
This distinction does not establish local liability or broker rules. Those depend on the instrument and account terms. Margin Accounts provides the separate foundation. The present lesson describes fund-return arithmetic and does not recommend borrowing to create or combine exposures.
Intraday entry changes the measured interval
Suppose a fictional benchmark begins its target day at 100 and an ideal +2x fund begins at $100. By a later point, the benchmark is 110 and the fund is $120. Someone entering at that moment has not owned the fund during the first part of its target interval.
If the benchmark ends the day at 115, the ideal full-day fund value is $130 under the simplified target assumption. From the later entry, the benchmark gained 115/110 - 1, approximately 4.55%, while the fund gained 130/120 - 1, approximately 8.33%. Twice 4.55% is about 9.09%, a different number.
The model has not failed to deliver the assumed full-day +2x return. The investor measured a different interval. Actual execution prices, intraday exposure changes and tracking add further complications. This exercise only isolates why a product's named daily target cannot automatically be assigned to every possible entry and exit time.
Costs and tracking belong in a second model layer
Start with the frictionless factors so the compounding mechanism is visible. Then add costs under an explicit convention. For a toy daily cost fraction c(t), one possible model factor is 1 + L × r(t) - c(t). That convention charges the assumed cost against starting daily wealth; a different timing convention should be described separately.
If the benchmark is flat for two days and the hypothetical cost is 0.01% each day, the fund factor is 0.9999 each day. A $100 balance ends at $99.980001, a loss of approximately 0.02%. This chosen cost is not a quoted expense for SSO or any other product. It shows where a model input enters the calculation.
Actual fund expenses, financing terms, derivative pricing and trading can have different bases and timing. They cannot always be represented by one constant deduction. Do not add an estimated cost twice when it is already embedded in an observed net return or instrument price. Define whether the data are ideal target returns, reported NAV returns or shareholder transaction returns before adjusting them.
A missed daily target is also different from correct daily tracking followed by multi-day compounding. The round-trip example needs no tracking error to end at $90. An actual fund might finish elsewhere because of implementation effects. Comparing its final return with twice the benchmark's cumulative return alone cannot isolate which mechanism caused the difference.
Extreme moves expose the model's boundary
In the simple +2x formula, a -30% benchmark day implies a -60% fund day, taking $100 to $40. Recovering from $40 to $100 requires a 150% fund gain, not 60%. Losses and recovery gains use different bases. This arithmetic illustrates severity; it does not predict a recovery path or promise that the target can be maintained through stress.
At a -50% benchmark move, the linear factor 1 + 2r reaches zero. Beyond that it becomes negative, which should not be reported as a precise negative ETF share price. The simplified model no longer describes feasible fund operation. Actual product terms, trading conditions and any liquidation or exposure-management provisions matter.
Even before that boundary, liquidity, valuation, counterparties and market interruptions can affect implementation. A neat spreadsheet should not be confused with a complete stress simulation. If a model cannot represent a mechanism, label the omission; do not infer protection from the absence of a row for it.
Compare multipliers on the same path
Apply an ideal +3x target to the earlier +25%/-20% benchmark round trip. The daily fund factors are 1.75 and 0.40. A $100 starting value becomes $175 and then $70, a 30% loss. The +2x version ended at $90. Increasing the target changes both the daily swings and their compounding interaction.
On two +5% benchmark days, the ideal +3x model instead returns 1.15 × 1.15 - 1 = 32.25%. Three times the 10.25% cumulative benchmark gain is 30.75%. These two examples use the same formula under different inputs; neither is evidence that a larger multiplier reliably improves an investor's result.
The correct comparison therefore includes the entire assumed return sequence, not only the benchmark's starting and ending values. If a worksheet presents one favourable path, add a round trip and a falling path using the same model conventions. This exposes how much of the conclusion was chosen through the inputs.
The two-day difference can be derived exactly
For two benchmark returns a and b, the cumulative benchmark return is a + b + ab. The ideal leveraged return is La + Lb + L²ab, because multiplying (1 + La) by (1 + Lb) creates the cross-product term. Multiplying the benchmark's cumulative return by L instead gives La + Lb + Lab.
Subtract the second expression from the first. The difference is L(L - 1)ab. This is an exact two-period identity under the frictionless model, not a forecast or a general formula for every real fund. It identifies the term missed by multiplying a cumulative benchmark result after the fact.
For L = 2 and the +25%/-20% round trip, ab is -0.05. The difference is 2 × 1 × -0.05 = -0.10, or negative ten percentage points. The benchmark's cumulative result is zero, so the model fund's return is -10%. This recovers the earlier answer by a second route.
For two +5% days, ab is +0.0025. The difference is +0.005, or half a percentage point: 21% versus 20.5%. With two -5% days the product is also positive, explaining why -19% is half a percentage point above -19.5%. The sign of the difference does not tell you whether the fund made money; it tells you its relation to one particular comparison.
This identity also distinguishes a compounding effect from a fee. The cross-product exists even when costs are zero. Adding realistic costs changes the outcome but does not explain away the underlying algebra. Calling every departure from a cumulative multiple “tracking error” would conflate separate mechanisms.
For more than two days, additional products of daily returns appear. The row-by-row wealth calculation is usually easier to inspect than an expanded expression. The two-day identity remains valuable as a small independent check: if a spreadsheet fails it, inspect the multiplier, percentage conversion and starting-value references before interpreting the output.
Account allocation creates another changing denominator
Consider an educational account model containing $10,000 in an ideal +2x daily fund and $10,000 in cash earning zero. Its starting benchmark exposure is $20,000 against $20,000 total wealth. That is one times account wealth initially, even though the fund itself has a +2x target. The two leverage ratios refer to different objects.
After a 10% benchmark rise, the fund becomes $12,000 and cash stays $10,000. Account wealth is $22,000. The fund's reset exposure is $24,000, approximately 1.09 times the account total. The original 50/50 allocation has drifted. An initial exposure match has not created a permanently matched account.
If the benchmark then falls 10%, the fund falls 20% to $9,600. Cash remains $10,000 and the account ends at $19,600, down 2%. The benchmark itself is down 1% over those two days. The discrepancy arises even though the account began with one-times exposure and the fund met both daily targets exactly.
A different model that resets the entire account to equal fund and cash values after the first day would have $11,000 in each. After the second day's fund loss, it would hold $8,800 in the fund and $11,000 cash, totalling $19,800. That is a different allocation rule with additional transactions; it is not an interchangeable description of the original account.
These examples are not portfolio recommendations. They demonstrate why fund-level resetting and account-level allocation must be modelled separately. Any actual comparison would also need transaction costs, cash interest, timing and execution assumptions. A simple initial ratio cannot stand in for those rules over an entire holding period.
Put the assumptions beside the output
Record the benchmark, multiplier, target interval and whether the objective is before expenses. For each day, calculate the benchmark factor and fund factor separately, update wealth, and reconcile the cumulative results. State that exact tracking is an assumption. Keep expense, execution and financing models on distinct lines so their effects can be identified.
Then compare at least two paths with equal benchmark endpoints. Show the daily returns that produce each endpoint, rather than assuming a positive and negative percentage cancel. Finally test the model's boundary with a large adverse move and explain why an invalid output should stop the calculation instead of becoming a trading claim.
Product-specific source dates should travel with the objective. If a provider changes the target horizon, benchmark or operating terms, the named example must be rechecked. The original hypothetical calculations remain useful only within their stated model; they do not override the new product documents.
Key takeaways and next lesson
A leveraged target has a horizon. Daily factors compound on changing wealth, so equal benchmark endpoints can produce different fund outcomes and a daily multiple is not a universal holding-period multiple. Resets, cash-flow timing, costs, execution and model boundaries must be separated. None of these calculations predicts the next path or recommends a product.
Continue with Measuring Portfolio Performance for cash-flow and return conventions, or Portfolio Risk for exposure aggregation. The worked models are educational illustrations, not forecasts, signals or investment advice.
Finished this lesson? Track your progress.
Frequently asked questions
Does a 2x ETF give twice the benchmark's return over a year?
A daily +2x target does not promise twice the annual cumulative return. Each day's fund return compounds on a changing base, and costs, tracking and the investor's transaction prices also matter.
Do leveraged ETFs always decay?
No universal always-loss rule follows from daily resetting. Different paths can produce results above or below the simple multiple of a cumulative benchmark return. Volatile round trips can reduce value in the ideal model, while persistent same-direction gains can produce a different relationship.
Does every leveraged ETF reset daily?
Read the individual product's stated target horizon. This lesson models daily reset funds and uses a labelled daily-target example; it does not assume every leveraged product has the same objective.
Is buying a leveraged ETF the same as borrowing in a margin account?
No. Fund-level exposure and an investor's account-level borrowing are different arrangements. This lesson models shares bought fully with cash; borrowing to buy them would add separate account obligations and risks.
Are the worked results forecasts?
No. They are arithmetic under exact daily tracking, specified hypothetical benchmark paths and stated omissions. Real funds can miss their targets and incur expenses, financing and trading effects.
Key terms
Next lesson
Continue learning
Measuring Portfolio Performance
Related topics
SPY: The S&P 500, the Fund and the Traded Share
Use SPY as a US-listed ETF case study to separate benchmark rules, fund ownership and exchange prices, with worked examples of weighting, costs and total return.
Portfolio Risk: Exposure, Scenario Losses and Model Limits
Calculate how holdings combine into portfolio losses, uncover overlapping exposures and distinguish volatility estimates from liquidity and funding risk.
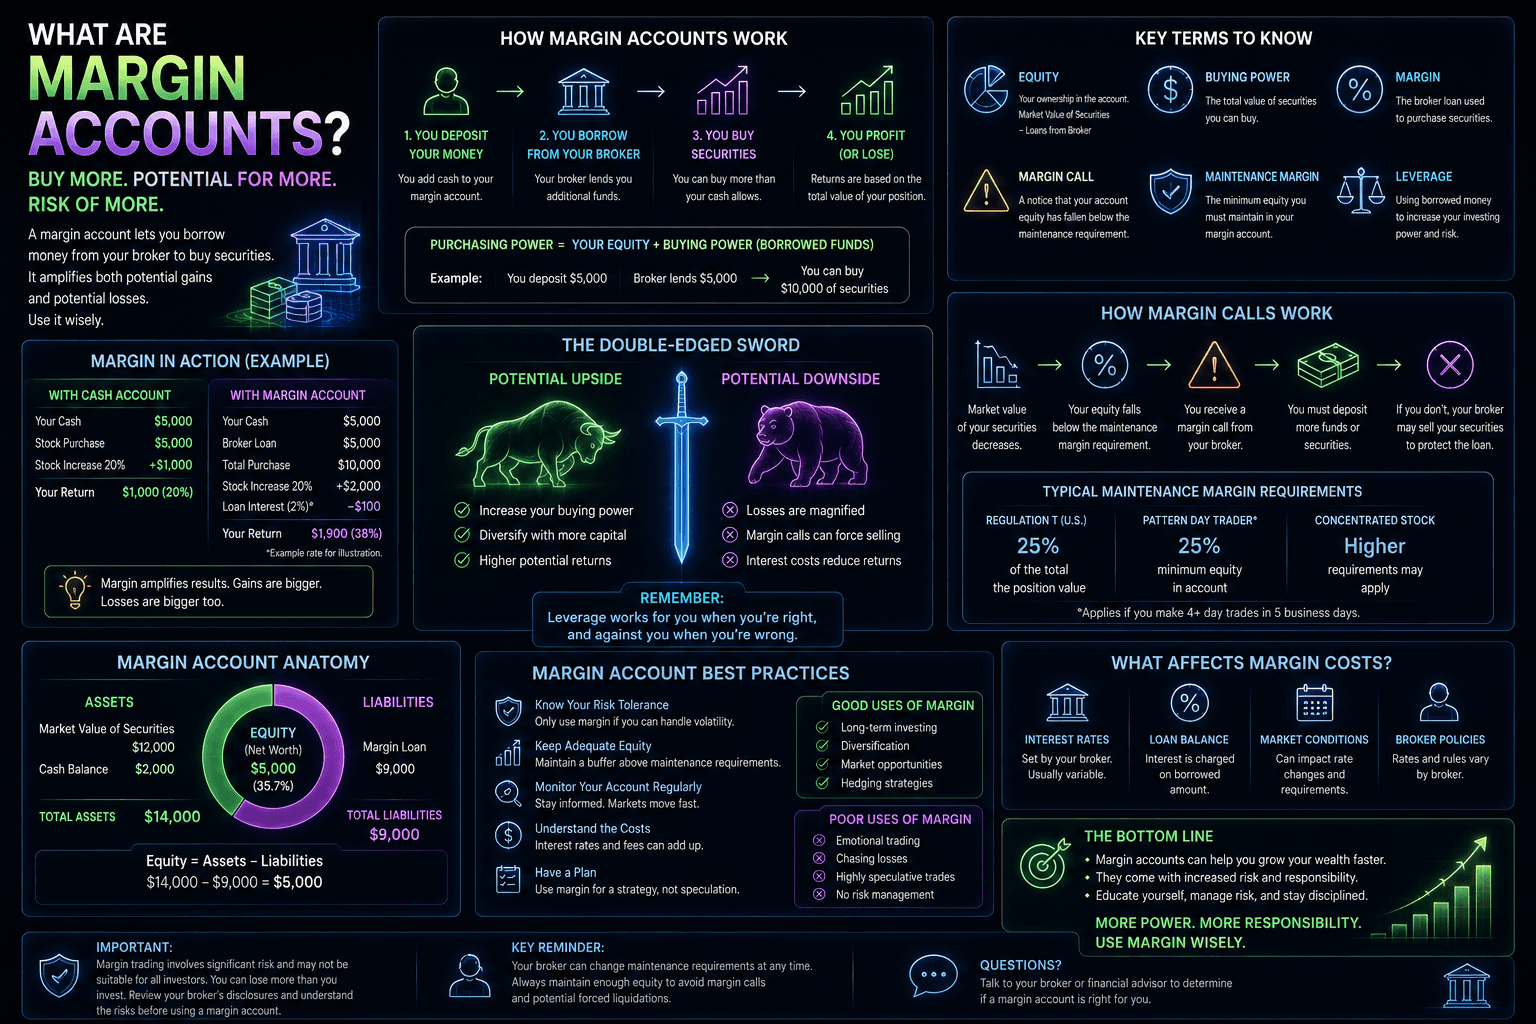
Margin Accounts
Borrowing to invest: how a margin account works, how leverage magnifies gains and losses alike, the mechanics and danger of margin calls and forced liquidation, the cost of margin interest, and why beginners should steer clear.
Ironclad Research provides educational content only. Nothing on this platform is financial advice, a recommendation, or an offer to buy or sell any security. Always do your own research and consider professional advice before making financial decisions.