Cede & Co: Understanding Securities Ownership
Trace US shareholdings through the issuer register, DTC participant accounts and broker records, with worked ownership and distribution reconciliations.
Written by James Lipyeat · Founder, Ironclad Research
Reviewed 9 October 2026 · Editorial policy
Before this, read
The question behind the unfamiliar name
This lesson concerns the United States securities holding system, specifically securities held through the Depository Trust Company, or DTC, and its nominee, Cede & Co. It does not describe every country's depository law or every way a US security can be held. The institutional descriptions were verified on 9 October 2026.
An investor looks at a brokerage statement and sees 100 shares. An issuer looks at its register and sees a much larger position under Cede & Co. These observations can both be correct. They come from different levels of a recordkeeping chain, with different jobs. Understanding those levels prevents a common mistake: treating several records of the same economic holding as several separate piles of shares.
This lesson builds on clearing and settlement and direct registration. Its distinct purpose is reconciliation: who records what, how the records connect, and how an event moves through the chain. It does not repeat the steps for requesting a registration transfer or recommend an arrangement. All companies, people, balances and distribution amounts in the examples are fictional. This is financial education, not advice.
Registered owner and beneficial owner
In the shareholder context discussed by Investor.gov, a registered owner holds shares directly on the company's records. A beneficial owner holds indirectly through a bank or broker-dealer. The latter is commonly described as holding in street name. These are descriptions of the holding relationship, not labels for genuine and imaginary investments. Source: Investor.gov, What is a registered owner? What is a beneficial owner?; verified 9 October 2026.
The word “owner” therefore needs its context. If an issuer asks who appears on its register, it is asking a different operational question from a broker identifying whose customer account is entitled to a holding. A statement about one record should not silently be substituted for a statement about the other.
Think of the distinction as a mapping problem. A top-level record can aggregate amounts that another record allocates across several accounts. Aggregation does not, by itself, erase the allocations. Equally, a customer statement does not show every institution or contract involved above it. A complete explanation connects the levels rather than choosing whichever document looks most familiar.
“Beneficial ownership” can also have specialised meanings in different legal and disclosure contexts. This lesson uses it for the basic shareholder holding arrangement, not as a complete definition for every reporting threshold or legal claim. Those questions need their own applicable rules.
What Cede, DTC and a broker each do
Cede & Co is DTC's nominee: the name used for registered holdings in the arrangement described here. DTC operates the depository records through which participating institutions hold and transfer interests. Brokers and custodians maintain further records connecting those positions to their own customers. Some customer-facing brokers use another firm for clearing or custody, so a real chain may contain more intermediaries than a simple diagram.
DTCC's issuer-services FAQ specifically distinguishes the issuer register, DTC participant positions and beneficial-owner information. It states that DTC has participant-level position information rather than the underlying beneficial-owner list. That distinction sets the boundary of what a DTC position report can establish. Source: DTCC Learning, Issuer Services FAQ, dated 29 November 2021; verified 9 October 2026.
An issuer's transfer agent maintains the issuer's shareholder records. A broker's trade execution function finds or arranges a transaction. A depository's records support holdings and transfers between participants. These are connected functions, but they are not interchangeable. In particular, the name on the issuer register does not identify the exchange or dealer that executed a customer's purchase.
It is possible to ask a sensible question of the wrong institution. A participant-position report can help an issuer identify intermediaries to contact. It cannot, by itself, explain every customer's cost basis or why one customer bought yesterday. A trade confirmation can describe an execution without being a complete map of registered holdings. First determine what the document was designed to record.
Worked example 1: reconcile a 240-share holding
Fictional Meridian Tools has 10,000 issued shares in this simplified exercise. Its register records 8,000 under Cede & Co and 2,000 under directly registered holders. Assume there are no treasury shares or other share classes in the model. The issuer-level check is 8,000 + 2,000 = 10,000.
DTC's participant records allocate the 8,000-share position as 5,000 to Participant A and 3,000 to Participant B. Participant A is assumed to hold only customer shares in this example. Its internal allocation is Maya 240, Noah 760 and other customers 4,000. The checks are 5,000 + 3,000 = 8,000 and 240 + 760 + 4,000 = 5,000.
Maya's brokerage statement can therefore show 240 shares even though the issuer register does not name Maya. Her amount is included within Participant A's 5,000, which is included within the 8,000 nominee position. Adding 240 + 5,000 + 8,000 would count overlapping levels, not independent issued shares.
| Record | Relevant balance | What it answers |
|---|---|---|
| Issuer register | Cede & Co: 8,000 | Registered nominee holding |
| DTC participant record | A: 5,000 | Portion held through this participant |
| Participant/customer records | Maya: 240 | Allocation to this customer |
Now suppose Maya acquires 50 settled shares from Noah, with both remaining under Participant A and no other activity. Her allocation becomes 290; Noah's becomes 710. Other customers remain at 4,000. The sum is still 5,000, so neither A's combined position nor the nominee total needs to increase in this simplified transfer.
Next consider a separate 50-share transfer from a customer under Participant B to Maya under A. A would rise to 5,050 and B would fall to 2,950. Their combined total would remain 8,000. The top-level register can be unchanged while the participant-level allocation changes.
These examples isolate record movements, not execution or settlement procedures. Actual processing involves transaction records, timing and controls absent from the small table. Their purpose is to show why a stable nominee total cannot establish that no beneficial-owner trading occurred underneath it.
Reconciliation needs matching dates and scope
The equalities above work because every figure refers to the same security, point in time and set of settled holdings. Remove that consistency and a difference becomes hard to interpret. A statement showing an executed purchase pending settlement is not necessarily comparable with a report containing only settled positions at an earlier cutoff.
For example, suppose a customer record shows 260 units after a 20-share purchase, while the comparison report predates the purchase and supports only 240. The 20-unit difference may have a straightforward timing explanation. But “may” is doing real work: without the trade and settlement records, it is a hypothesis, not a verified reconciliation.
A methodical comparison identifies the security and share class, the account or participant, the relevant date and cutoff, and whether amounts represent settled positions, pending transactions or other obligations. It then accounts for documented movements. Any remaining discrepancy needs investigation instead of being forced to fit a preferred narrative.
This matters in both directions. An unexplained difference is not automatically evidence of duplicate issuance or wrongdoing. It is also not something to dismiss merely because aggregation is common. The right conclusion follows from evidence that connects the records, with unresolved items labelled as unresolved.
Worked example 2: change registration without changing the total
Return to the original balances: 8,000 shares registered under Cede & Co, 2,000 under other registered holders, and Maya's 240 within Participant A's 5,000. Suppose, solely to illustrate the accounting, that 100 of Maya's shares are transferred into direct registration in her name. Assume eligibility and processing have been confirmed, and that the transfer completes without another transaction.
The nominee register position falls to 7,900. Maya appears for 100 directly registered shares, alongside the 2,000 already registered to others. The issuer total is still 10,000: 7,900 + 100 + 2,000. Participant A's position falls to 4,900; Maya's broker allocation falls to 140. Her combined holding is 140 + 100 = 240.
| Item | Before | After |
|---|---|---|
| Nominee register position | 8,000 | 7,900 |
| Other directly registered holdings | 2,000 | 2,000 |
| Maya's directly registered position | 0 | 100 |
| Issuer total in the model | 10,000 | 10,000 |
| Maya's broker allocation | 240 | 140 |
| Maya's combined holding | 240 | 240 |
It would be wrong to retain all 240 in Maya's broker allocation and also add the 100 directly registered shares when describing the completed transfer. That would treat a movement as an acquisition. The SEC's investor bulletin makes the same basic distinction: changing the holding arrangement does not mean the shares exist in both places simultaneously. It also explains that available holding methods depend on the security and provider. Source: Investor.gov, Holding Your Securities, 12 July 2023; verified 9 October 2026.
Reverse the hypothetical movement and the quantities reverse too: the nominee allocation rises by 100 while Maya's directly registered balance falls by 100. Neither direction is a share issue, a stock split or a company repurchase. Those are different events with different effects on capital and records.
This example does not establish an execution speed, fee, tax result or preferred registration method. It isolates the conservation of quantity across a completed transfer. The separate DRS lesson covers the holding arrangement; current provider terms govern any actual process.
How a cash distribution moves through the records
An issuer-level event has to reach the investors entitled to it. In the depository arrangement, the register and participant records help allocate amounts through intermediaries. That process explains why a customer may receive a credit from a broker rather than a payment bearing the issuer's own name. A nominee entry is part of a distribution chain, not proof that the intermediary retains the customer's entire economic benefit.
DTCC describes DTC's processing of distributions and participant-level positions in its issuer-services material. Its separate explanation of Security Position Reports describes how issuers identify participating intermediaries, rather than obtaining every underlying investor directly from the depository's books. Source: DTCC, Security Position Reports Help Reach Shareholders; verified 9 October 2026.
For an original numerical illustration, use the initial 10,000-share model and assume a $0.25 gross cash distribution per eligible share. All holdings are settled and eligible at the relevant record point. There are no loans, deductions, taxes, fees or disputed entitlements. The total gross allocation is 10,000 × $0.25 = $2,500.
The nominee portion corresponds to 8,000 × $0.25 = $2,000; the directly registered portion corresponds to $500. Within the depository portion, Participant A's 5,000 shares correspond to $1,250 and B's 3,000 to $750. Within A's allocation, Maya's 240 shares correspond to $60, Noah's 760 to $190, and other customers' 4,000 to $1,000. Those three amounts sum to $1,250.
The figure is an allocation model, not a claim that the exact cash transfers occur as separate payments in that sequence or on the same day. Real systems may process many events together. The learner's task is to reconcile the entitlement amounts without double-counting them.
If Maya's actual credit were $57 in an otherwise similar example, the $3 difference would require an explanation. A documented deduction might reconcile it; an invented one would not. The gross calculation supplies a starting point, while statements and event records supply the reasons for differences. The lesson does not assign a universal tax rate or investor-protection outcome.
Voting involves a separate instruction chain
Cash allocations and voting rights are related to holdings, but they are not the same process. A register balance does not tell you how a beneficial owner wants to vote. Communicating meeting information, determining relevant positions, collecting instructions and tabulating votes require further steps.
DTC describes an omnibus proxy that assigns voting rights to participants holding positions on the record date. Those participants then act through their established processes on behalf of beneficial owners. This is why the nominee name on a register should not be interpreted as a single investment opinion directing all underlying votes. Source: DTCC, Proxy Services; verified 9 October 2026.
A simple hypothetical illustrates the distinction. Assume Participant A has 5,000 voting entitlements for a fictional meeting, with one vote per eligible share. Customer instructions received through its process concern only 3,600. The arithmetic leaves 1,400 for which the example has not supplied instructions. It does not tell us how those 1,400 will be treated. That depends on the applicable rules, proposal and procedures, none of which the balance alone establishes.
Similarly, a customer holding 240 shares today cannot infer an entitlement for a past record date without checking the relevant position. Holdings change; event eligibility is tied to the event's terms. No universal deadline or default voting treatment is asserted here. The purpose is to separate quantity, eligibility and instruction, rather than collapse them into one number.
Distinguish a position from a movement
A position is an amount at a specified point. A movement is a change between points. Confusing them can make ordinary recordkeeping look inconsistent. Suppose Participant A begins with 5,000 shares, receives 300 from other participants and delivers 200 during a fictional interval. With no other movements, its ending position is 5,100. Gross incoming and outgoing activity totals 500, while the net change is only 100.
An issuer examining only the beginning and ending participant reports can observe the 100-share net increase. It cannot recover the full 500 of gross movements from those two balances alone. Still less can it determine the number of customers involved or their reasons. Many different sequences could lead to the same ending position.
For a second sequence, A could receive 1,100 and deliver 1,000, also ending at 5,100. The two examples have different gross activity but identical beginning and ending positions. This is why changes in a nominee or participant balance should not be relabelled as total trading volume. Stocks and flows answer different questions.
The same reasoning applies to a customer's statement. An opening balance of 240 and a closing balance of 240 do not prove that nothing happened. The customer could have bought and sold equal quantities during the period. A holdings page and a transaction history are complementary records, not substitutes for one another.
For a complete small reconciliation, write opening position plus documented receipts minus documented deliveries, then account separately for any corporate-action adjustments. Compare that result with the closing position. Keep pending movements separate until their status is understood. The method makes the missing evidence visible without guessing at it.
In the model, 5,000 + 300 − 200 = 5,100 is sufficient. If an actual report instead shows 5,080, the remaining 20-share difference is a question to investigate. It might concern an omitted movement, an adjustment or mismatched scope; the arithmetic does not choose among those possibilities. A useful explanation names the unresolved item and the record needed to resolve it.
What the chain cannot prove
An aggregate nominee holding is not evidence that Cede made a single investment decision to acquire that amount. A participant position is not a list of all the end investors' names. A customer statement is not a guarantee that operational mistakes are impossible. Each record has a specific scope, and its strengths do not remove its limits.
Nor does the existence of an intermediary chain settle every question about legal rights or insolvency. Those depend on the security, account arrangement and applicable law. This article does not substitute a diagram for a legal analysis or imply that moving between holding arrangements removes every risk. The market value of the underlying security can still change in any arrangement.
Securities lending introduces another distinction: the obligation to return equivalent securities is different from an ordinary unloaned holding. The clean settled-position equations above intentionally exclude loans. Applying them to a lending book without recognising those obligations would hide the very differences a reconciliation is supposed to explain.
That is why securities lending is the next lesson. It follows the loan, collateral and return obligations separately. A reader who can already distinguish issuer, participant and customer records has a stronger foundation for understanding that additional layer.
A final reconciliation exercise
Suppose a second fictional issuer has 20,000 shares: 15,000 in the nominee position and 5,000 directly registered. Participant C accounts for 6,000 of the nominee shares and Participant D for 9,000. A customer under C holds 300. If 80 of that customer's shares move to direct registration, the completed model becomes 14,920 in the nominee position, 5,080 directly registered, C at 5,920 and D at 9,000. The customer has 220 through C and 80 directly registered.
Every relevant total reconciles: 14,920 + 5,080 = 20,000; 5,920 + 9,000 = 14,920; 220 + 80 = 300. No new shares or investment return have appeared. The example changes the location of a registration record while preserving the overall quantities.
If a supplied document still shows C at 6,000, the next question is its timing and status. Was it generated before completion? Does it include a pending item? Is a different account being compared? If the evidence does not answer those questions, the correct result is an unresolved difference, not a confident story about what must have occurred.
Source scope and maintenance: US institutional descriptions were verified on 9 October 2026 using the linked SEC/Investor.gov and DTCC materials. Recheck after changes to DTC's nominee, participant-reporting, proxy or registration services. Publication dates are identified where available and are separate from verification dates. This article does not re-verify every claim in older linked lessons, set transfer fees or deadlines, or recommend a registration change.
Finished this lesson? Track your progress.
Frequently asked questions
What is Cede & Co?
Cede & Co is the nominee associated with the Depository Trust Company, or DTC. Its name appears as registered holder for securities held through that US depository arrangement.
Does Cede & Co's registered position mean customers do not own their investments?
No. Registered and beneficial ownership describe different records and relationships. A customer can hold a beneficial interest through intermediaries while the issuer's register names the depository nominee.
Does DTC keep every retail investor's name?
DTC's issuer-services explanation distinguishes participant-level position information from beneficial-owner records maintained further along the intermediary chain. Its participant report is not a complete retail shareholder list.
Does moving shares into direct registration create more shares?
No. In the simplified transfer example, the nominee position decreases by the same quantity added to the investor's registered position. The holding arrangement changes; the issuer's total does not.
Does this lesson recommend a holding arrangement?
No. It explains US ownership records and reconciliation. It does not recommend moving holdings or claim that any registration arrangement removes every investment or operational risk.
Key terms
Next lesson
Continue learning
Securities Lending
Related topics
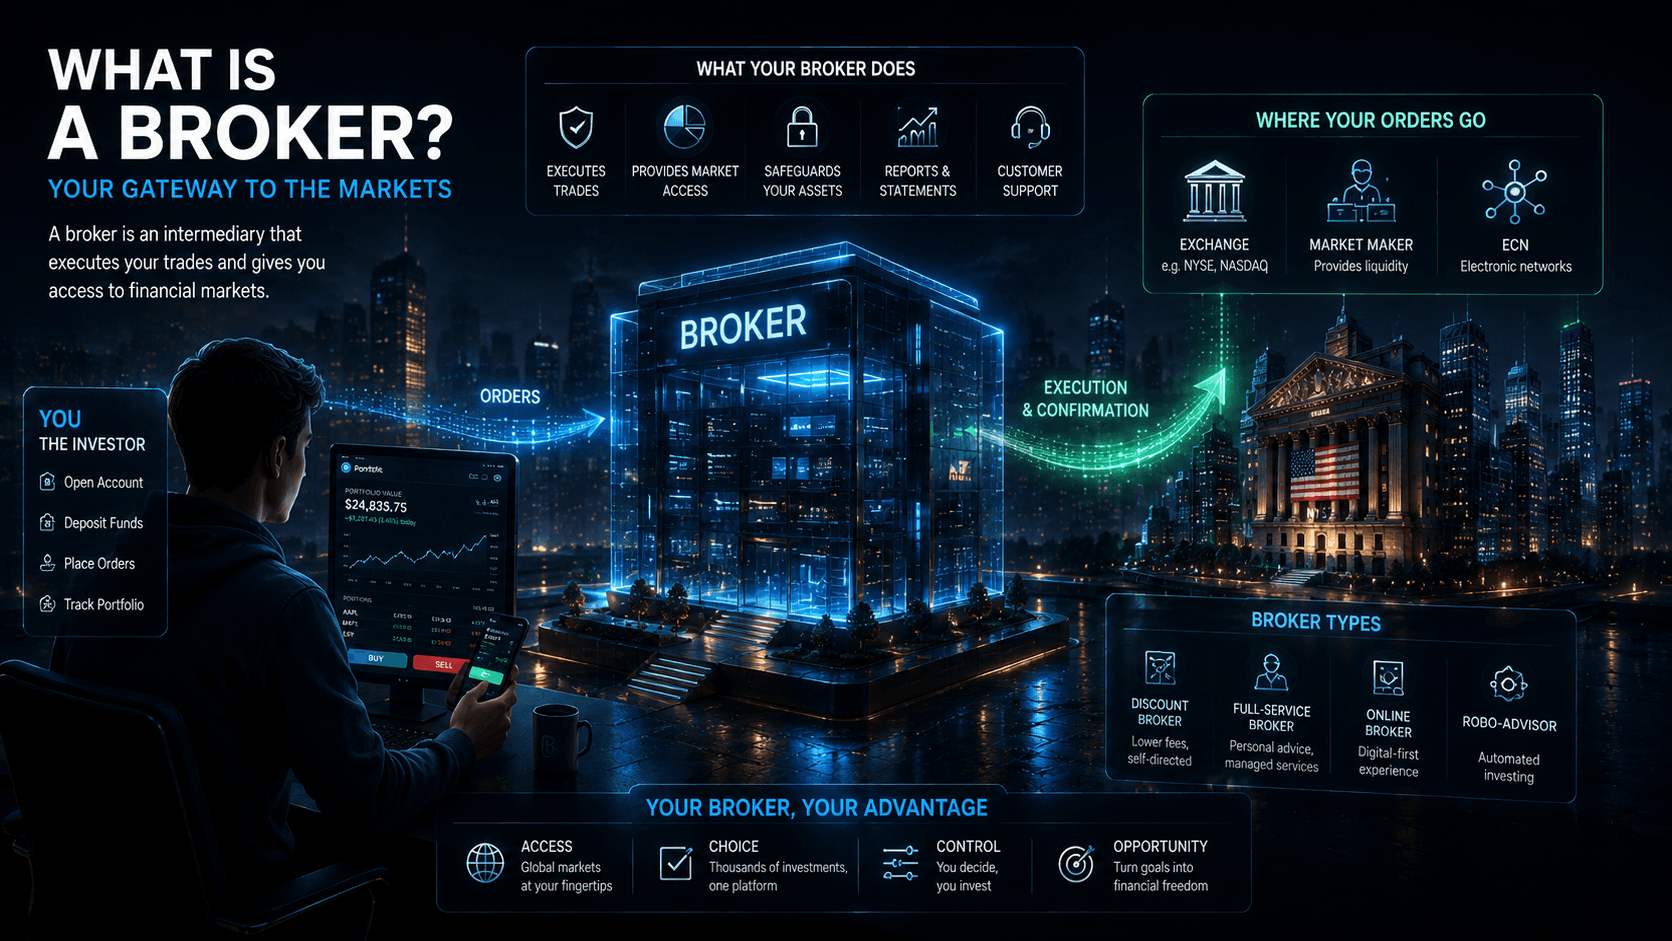
What Is A Broker?
A complete guide to brokers: what they do, why you need one, how they actually make money, the journey of an order, how your shares are held, and how to choose one safely.
Outstanding Shares
How many shares a company actually has: the difference between authorised, issued, outstanding and treasury shares, how the count changes through issuance and buybacks, what dilution means for your ownership, and why the outstanding count underpins ownership percentage, earnings per share and market cap.
Ironclad Research provides educational content only. Nothing on this platform is financial advice, a recommendation, or an offer to buy or sell any security. Always do your own research and consider professional advice before making financial decisions.